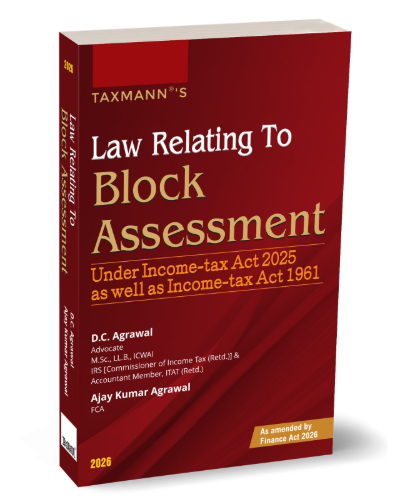
Law Relating to Block Assessment (Under Income Tax Act 2025 as well as Income Tac Act 1961
As amended by Finace Act, 2033
Key Highlights
- Reproduces every key provision verbatim with clause-by-clause analysis, integrates over 2,500 judicial precedents, and offers a comprehensive 1961 ↔ 2025 section mapping.
- Reads the new framework against the entire body of Chapter XIV-B jurisprudence developed between 1995 and 2003 and refined through litigation thereafter — asking, provision by provision, which doctrines survive, which evolve, and which are displaced.
- The only block assessment treatise that simultaneously serves as a working manual under the 2025 Code and as a continuing reference to the 1961 Act for ongoing litigation, appellate proceedings, and pre-2026 search cycles.
- Distinguished by its Manner-of-Operation/Example/Defence treatment for forensic chapters, a case-by-case Section 65B digital evidence taxonomy, and a dual-lens approach covering both assessing-authority and taxpayer-defence perspectives.
- Provides clear section-mapping tables between old and new law codes, and explains the complex rules of digital evidence admissibility clearly.
- Logically organises the massive topic into five progressive analytical blocks — covering everything from basic notice mechanics to complex undisclosed digital wealth valuations.
Law Relating to Block Assessment is the leading contemporary treatise on India's revived block assessment regime under Chapter XVI-B of the Income-tax Act 2025, as amended by the Finance Act 2026 and effective from 1st April 2026. Authored by D.C. Agrawal and Ajay Kumar Agrawal, this Edition uniquely reads the new Code against three decades of Chapter XIV-B jurisprudence — asking, provision by provision, which doctrines survive, evolve, or stand displaced. The reintroduction of block assessment through the Finance (No. 2) Act 2024, its refinement by the Finance Act 2025, its consolidation under the Income-tax Act 2025, and its further amendment by the Finance Act 2026 has fundamentally reshaped the architecture of search-driven taxation in India — returning, after two decades of search assessments under Sections 153A to 153C, to a consolidated block mechanism in a modernised form that incorporates digital assets, quarter-based limitation, mandatory supervisory approvals, and harmonised integration with the deemed income regime.
Related Legal Commentaries & Titles
माध्यमिक शाळा संहिता | Secondary School Code
Adv. Sudhir Birje
₹397
महिला बचत गट | Handbook for Self- Help Women Group
-
₹112
Law Relating to Women & Children
Mamta Rao
₹761
Criminal Law
P.S.A. Pillai
₹2070
Criminal Law: Cases & Materials
K.D. Gaur
₹1615
Textbook on The Bharatiya Nyaya Sanhita, 2023 (BNS 2023)
K. D. Gaur
₹1345